

Green Iron in Labrador. Is Iron Bear Still in Play?

Green iron needs a grade of iron ore that few mines produce, and the Labrador Trough in eastern Canada is one of the places that produces it. This Samso Insight lists the mines and projects in the Trough, sets out what the Canadian government is offering, and then looks at Iron Bear Resources (ASX: IBR) now that Vale has left the project. Iron Bear's concentrate tested inside the green iron specification, and the company again owns all of the project.


On 7 October 2026 the Institute for Energy Economics and Financial Analysis, known as IEEFA, published a piece that compared Canada with Australia in the supply of green iron [R1]. IEEFA is a research body that writes about energy and heavy industry. Its conclusion was that Australia may not compete head-to-head with Canada in this market. The Labrador Trough is the centre of its argument.
Samso has written about the Labrador Trough many times, mostly through Iron Bear Resources (ASX: IBR), which was called Cyclone Metals until January 2026. Three weeks before the IEEFA piece, Vale told Iron Bear that it would not fund the next stage of the Iron Bear project [R3]. Vale is the Brazilian miner that had the right to earn 75 per cent of it.
The Canadian government announced support for the district on 17 August 2026. A month later Iron Bear, the Labrador Trough project with the largest production plan, lost its funding partner. Figure 1 shows where the Trough is.

All share prices in this piece are as at the close of ASX trading on 7 October 2026.
WHAT THIS PIECE COVERS 1.00 What IEEFA said The comparison between Canada and Australia, and the four points IEEFA makes about Canada. 2.00 Green iron and the ore it needs What direct reduction is, the grade of ore it needs, and what the forecasters say. 3.00 The mines operating in the Trough Five operators, what each produces, and who is already upgrading. 4.00 The projects not yet built Kami, Lac Virot, Lac Otelnuk and the smaller ones, with the stage each has reached. 5.00 What Canada is offering The hydro package, the corridor, the approvals bill, and what none of them promises. 6.00 Iron Bear, the resource and the study What the July 2026 Pre-Feasibility Study says about the reserve, the costs and the power line. 7.00 Vale leaves The terms Vale had, what it spent, and what it declined. 8.00 Does Iron Bear still need a partner? What Samso said before, and what the numbers say now. 9.00 Iron Bear's market capitalisation Samso's arithmetic on the market capitalisation, with the reasons the market may be right. 10.00 The case against Why green iron may arrive late, and what stands between a project this size and its funding. 11.00 Samso view What the IEEFA piece means for an Iron Bear shareholder. |
A NOTE ON THE VOCABULARY AND THE SOURCES Each technical term is explained where it first appears, and all of them are collected in one box at the back, above the references. A marker such as [R2] points to the numbered source in the reference list that supports the sentence it follows. Noel Ong, who writes for Samso, holds shares in Iron Bear Resources. |
1.00 — WHAT IEEFA SAID
IEEFA's four points on Canada and its view of Australia
The IEEFA piece was written by Soroush Basirat, an analyst in its Australian office [R1]. It makes four points about Canada.
The first is that Canada already mines the right ore. IEEFA says the Labrador Trough has produced high-grade iron ore since 1954 and now produces about 50 million tonnes a year. It names Canada as one of the largest exporters of the pellets used in green iron, alongside Brazil, Sweden and Bahrain.
The second is that the existing mines are being upgraded. IEEFA names ArcelorMittal and Champion Iron as two companies spending money to lift their product from the grade a blast furnace uses to the grade that green iron needs.
The third is that Canada put high-purity iron ore on its list of critical minerals in 2024. Australia has not. IEEFA notes that iron ore is Australia's highest-value export and is not on the Australian list.
The fourth is approvals and power. IEEFA points to a federal bill built around the phrase “one project, one review, one year”, and to what the Canadian Prime Minister called the largest clean energy investment in North American history.
IEEFA's last paragraph names two projects as the new generation of high-grade supply. One is Champion Iron's Kami project. The other is Iron Bear. IEEFA's closing judgement on Australia is that the country “may not compete head-to-head with Canada in this evolving market” [R1].
Australia's side of the comparison is short. IEEFA says Australia can produce almost 65 million tonnes a year of magnetite concentrate, and that none of it currently meets the green iron specification. Magnetite is the magnetic iron mineral, and concentrate is the powder left after the waste rock has been removed.
2.00 — GREEN IRON AND THE ORE IT NEEDS
How direct reduction works and the ore it needs
Most of the world's iron is made in a blast furnace. Iron ore goes in with coke, which is coal that has been baked. The coke supplies the heat and also strips the oxygen out of the ore. Carbon dioxide comes out of the top.
Direct reduction is a different process. It strips the oxygen out of the ore with natural gas or hydrogen, at a temperature below the melting point of iron. The product is a solid called direct reduced iron, or DRI. The DRI is then melted in an electric arc furnace, usually shortened to EAF. When the gas is hydrogen made with clean electricity, the DRI is called green iron.
A blast furnace melts everything, so the impurities in the ore float off as slag, which is the molten waste skimmed from the top. Direct reduction never melts the ore. Silica and alumina are the two main waste minerals in iron ore. Whatever silica and alumina go in with the ore are still there when the DRI reaches the electric furnace, and the steelmaker pays to remove them. So the process needs ore with very little of either.
Samso has written about direct reduction and DR pellets in two earlier Samso Insights. The first was Direct Reduction Iron – The Iron Ore Opportunity Investors May Be Missing, published on 11 March 2026. The second was Direct Reduction (DR) Pellets and Green Steel – Who are the Industry Leaders?, published on 22 April 2026.
The International Iron Metallics Association, writing in the journal of the Midrex company, puts the specification at more than 66 per cent iron and ideally more than 67 per cent, with silica and alumina together at no more than 3.5 per cent and ideally 2 per cent or less [R27]. Midrex is the company behind the most widely used direct reduction process. Ore that meets this specification is called DR-grade iron ore. The main price index for the ore Australia sells is set on 62 per cent iron.
DR-grade ore is usually sold as pellets. A pellet is a marble-sized ball made by rolling concentrate and baking it hard, so that gas can flow between the balls inside the furnace. Plate 1 shows pellets made from Iron Bear ore in a test.

How large the market is now
Midrex counted 151.0 million tonnes of DRI produced in the world in 2025, up 7.2 per cent on 2024 [R28]. IEEFA's March 2026 report says less than 10 per cent of the world's iron is made by direct reduction, and that only about 31 per cent of DR-grade pellets were traded by sea in 2024 [R26].
What the forecasters say
The same IEEFA report sets four forecasts side by side. Samso has read IEEFA's report and has not read the four forecasts themselves.

Six of the seven forecasts in Table 1 show a shortfall, and one Midrex scenario shows a surplus. The shortfalls run up to 133 million tonnes a year. The largest shortfalls are forecast for 2035 and 2040.
The premium in September 2026
On 8 September 2026 the benchmark price for 62 per cent ore delivered to China was US$98.70 a tonne, and the price for 65 per cent ore was US$117.50 [R29]. DR pellets earn a further premium on top of the 65 per cent price. Labrador Iron Ore Royalty Corporation, which owns part of Iron Ore Company of Canada, reported that premium at US$43 a tonne for the June quarter of 2026 [R17].
Samso wrote in April 2026 that plenty of juniors talk about DR-grade concentrate and very few have delivered commercial DR pellets [R41]. Its conclusion said “The main aspect of this DR pellets story is to identify those that can and those that are using the term to promote”.
3.00 — THE MINES OPERATING IN THE TROUGH
The five iron ore operators in the Labrador Trough
The Labrador Trough is a belt of iron-bearing rock about 1,100 kilometres long [R13]. Most of the ore in the ground is low grade, at around 30 per cent iron. The mines crush it, separate the iron minerals from the waste and ship a concentrate or a pellet at 63 to 69 per cent iron. Figure 2 shows where the operators are.

Natural Resources Canada, the federal department, records that Canada produced 70 million tonnes of iron ore in 2024 and that 60 per cent of it came from Québec [R25]. The rest came from Newfoundland and Labrador and from Nunavut. It gives no figure for the Trough alone. IEEFA's source for the 50 million tonnes is Iron Bear's website. Table 2 lists the five operators.

Iron Ore Company of Canada
This operation owns the 418-kilometre railway to the port at Sept-Îles. Labrador Iron Ore Royalty Corporation reported 15.9 million tonnes of saleable product in 2025 at an average price of about US$109 a tonne [R16]. The June 2026 quarter was weak. Saleable production fell 31 per cent on a year earlier, and the royalty company said the mine was catching up on waste removal it had deferred and that this would take several years [R17].
ArcelorMittal
ArcelorMittal announced in November 2021 that it would convert its whole 10 million tonne a year pellet plant at Port-Cartier to DR pellets for C$205 million, and finish before the end of 2025 [R21]. In August 2026 the Canadian publication The Logic reported a federal commitment of C$125 million and completion in early 2029 [R22]. The two documents are about three years apart on the finish date. IEEFA uses 2029.
Champion Iron
Champion Iron (ASX: CIA) is the only ASX-listed company whose main business is a Labrador Trough mine. Its Bloom Lake mine produced 3.5 million tonnes of concentrate at 66.5 per cent iron in the June 2026 quarter, at a cash cost of C$83.4 a tonne [R18]. Cash cost is what it costs to mine, process and deliver a tonne, before interest, tax and new capital. The company made a net loss of C$41.5 million in that quarter.
Champion has spent C$493.7 million of a C$500 million budget on a plant that lifts half of Bloom Lake's output to 69 per cent iron, which is DR-grade [R18]. The new plant produced 0.6 million tonnes of concentrate in the quarter while its quality was still being lifted. Champion has a commercial agreement for part of the plant's expected near-term output, and expected the first shipment in the September quarter of 2026 [R46]. We found no report that the first cargo has sailed. That is what we found, but we have not been able to verify it.
Figure 3 puts the DR-grade tonnes planned across the Trough on one chart. The two upgrades at operating mines are the tonnes most likely to arrive first.


4.00 — THE PROJECTS NOT YET BUILT
Kami and four other undeveloped projects
A mining project moves through a series of studies before anyone builds it. A scoping study or preliminary economic assessment (PEA) is the first rough estimate. A Pre-Feasibility Study (PFS) is the second and narrows the options. A Definitive or Bankable Feasibility Study (DFS or BFS) is the detailed version a bank will lend against. Table 3 lists the Trough projects by the study each has reached.
A Mineral Resource is the tonnage a company estimates is in the ground and has a reasonable prospect of being mined. An Ore Reserve is the part of the resource that a study has shown can be mined at a profit. Australian companies report both under the JORC Code, the Australian rulebook for these estimates. Canadian companies use a similar code.

Kami
Kami is near Wabush, close to Bloom Lake. Champion's study of January 2024 put the capital cost at C$3,864 million, which was US$2,972 million at the time [R20]. It gave two results. At a long-term price of US$120 a tonne for 65 per cent ore, the project returned 9.8 per cent a year after tax. At the average price of the three years before the study, it returned 14.8 per cent.
A return of 9.8 per cent is 1.8 percentage points above the 8 per cent discount rate used in the study. Champion did not go ahead alone. In 2025 it brought in two Japanese partners. Nippon Steel is a steelmaker, and Sojitz is a trading house. Together they agreed to contribute C$245 million to a new partnership that owns the project, and they hold 49 per cent of it [R19]. They contributed C$68.6 million at the first closing. The other C$176.4 million is due only when the DFS is complete and the partners decide to continue.
That figure is useful because it is money committed for a known share of a Trough project at the PFS stage. Section 9.00 uses it as a comparison.
Kami is the only iron ore project named in the Canadian Prime Minister's announcement of 17 August 2026 [R12]. The release also names a graphite project, a port and rail project and a transmission study. The federal government will support planning and feasibility work on the transport and energy that Kami needs. The announcement gives no dollar figure for Kami.
The four other projects
Lac Otelnuk is the largest deposit on the list at more than 20 billion tonnes, on an estimate its owner no longer treats as current. Labrador West and Lac Virot are much smaller. Joyce Lake is a short-life project selling ordinary ore and is outside the green iron discussion. Samso found no funding partner announced for any of the four. Joyce Lake's stage in Table 3 is as at Century's June 2026 filing.
5.00 — WHAT CANADA IS OFFERING
The hydro package, the corridor, the approvals bill and the critical minerals list
IEEFA lists four measures. This section sets out what the government document behind each one says.
The hydro package
IEEFA says the Canadian government announced an investment of C$70 billion in clean energy. The Prime Minister's release says something narrower [R12]. The projects together are worth “nearly $70 billion”. The federal contribution is “$10 billion in federal financing”. The release does not say whether that C$10 billion is a loan, a guarantee or a grant, and it does not say who pays the other C$60 billion.
The projects are an upgrade and expansion of the Churchill Falls hydro station in Labrador, a new station at Gull Island, the transmission lines for both, and a wind project. The release puts the total at 14,000 megawatts.
The corridor
On the same day the government referred the “Labrador Trough Clean Power, Critical Minerals and Infrastructure Corridor” to its Major Projects Office [R13]. The corridor page names the two hydro stations, the Port of Sept-Îles and the two provincial power utilities. It names no mining company.
Referral and designation are two separate steps. Designation as a project of national interest is the step that brings conditional federal approvals up front and a target of proceeding within two years [R37]. The corridor page records a referral, which is the earlier of the two steps.
The approvals bill
The Building Canada Strong Act was introduced to Parliament on 21 September 2026 [R14]. It would require federal reviews to finish within one year of a complete application. The bill has not been passed. It would build on an earlier law, Bill C-5, the One Canadian Economy Act of June 2025, which created the national interest pathway.
The critical minerals list
Canada added high-purity iron ore to its critical minerals list on 10 June 2024, with the sentence “High-purity iron ore is essential to green steel and integral to decarbonization” [R15]. The release says the list guides federal policy and programs. It names no fund that a listed mineral automatically qualifies for.
What this means for a project owner
Canada has committed C$10 billion of financing towards power and has introduced a bill to shorten approvals. Those are the two things a single mining company cannot arrange alone. The hydro and transmission would benefit every project in the Trough. The money for a mine, a concentrator and a pellet plant still has to come from the owner and its partners.
Iron Bear told the ASX on 24 September 2026 that these measures benefit its project [R8]. The same announcement says the company “will continue to monitor” the corridor. Iron Bear announced on 3 June 2026 that it had applied to the Major Projects Office for recognition as a project of national significance, with the aim of cutting federal permitting from about five years to two [R10]. The company has not announced a decision on that application.
6.00 — IRON BEAR, THE RESOURCE AND THE STUDY
The Iron Bear resource, the July 2026 PFS and the power line
Iron Bear is about 30 kilometres north-west of Schefferville. The deposit is a magnetite iron formation. The rock holds about 30 per cent iron. About 21 per cent is iron in magnetite, which is the part the plant recovers.
The resource and the reserve
Iron Bear's resource is 13.6 billion tonnes at 30.03 per cent iron, estimated in May 2026 [R6]. Of that, 4.5 billion tonnes is in the Indicated category, which is the middle level of confidence, and 9.1 billion tonnes is Inferred, the lowest. The earlier estimate was 16.6 billion tonnes. The total fell 18 per cent. The company put this down to a revised geological interpretation, new pit parameters and a stricter test of what could be mined. In the same update the Indicated tonnage rose from 2.1 to 4.5 billion tonnes, which the company said came from new classification criteria. The estimate uses drilling from 2011 and 2012.
The PFS of 29 July 2026 declared the first reserve, at 3.3 billion tonnes at 29.1 per cent iron [R2]. All of it is Probable, the lower of the two reserve categories. A reserve can only be drawn from the Indicated or higher categories. The mine plan processes 3.4 billion tonnes, which is about a quarter of the resource. About 5 per cent of that is Inferred material that is outside the reserve.
What the study plans to build
The base case is a mine that runs for 44 years and sells 23 million tonnes a year at full rate [R2]. Of that, 18.4 million tonnes is DR pellets and 4.5 million tonnes is concentrate for blast furnaces. The DR concentrate tested at 71.0 per cent iron with 1.2 per cent silica and alumina together, which is inside the specification in section 2.00. The study's test table gives the pellets made from it as 68.4 per cent iron.
The project is built in three stages. Stage 1 starts at 5.4 million tonnes a year. Full rate comes in about year 11 of production. Figure 4 shows the build-up. For the first four years the project sells only blast furnace concentrate. The DR pellets come with Stage 2, because the pellet plants are built in Stages 2 and 3.

The headline numbers
Net present value, or NPV, is the cash a project is forecast to earn over its life, less what it costs to build and run, with later years counted for less. The rate used to count them down is the discount rate. Internal rate of return, or IRR, is the yearly return the project earns on the money put into it. Table 4 sets the PFS beside the scoping study it replaced.

Table 4 shows the NPV fell from US$9,792 million to US$9,007 million while most of the inputs moved. The return fell from 18.6 to 15.2 per cent. Payback went from under seven years to about ten. The operating cost of a tonne of pellets rose by about US$19. Samso's reading is that four changes offset the higher costs. The mine life more than doubled, the price assumption rose, more of the product is pellets, and the power line moved out of the capital cost. The study assumes a DR pellet price of US$212.3 a tonne delivered to the customer, in today's dollars, and most of the value rests on that price [R2].
The study's cash flows include inflation of 2.5 per cent a year, and the 8 per cent rate is applied to those inflated figures. The study's sensitivity table shows the NPV falling from US$9.0 billion to US$5.4 billion if that rate is 9.6 per cent. So the 8 per cent rate and the 15.2 per cent return both include inflation.
The power line, the power price and the cost of Stages 2 and 3
The power line is not in the capital cost. The project needs about 342 kilometres of transmission line from Churchill Falls. The PFS assumes a third party builds and owns it, and quotes an estimate of about US$3.1 billion from the engineering firm Hatch [R2]. The scoping study had power inside its capital estimate. Samso's reading is that this is one reason the capital figure did not rise between the two studies. The first stage is also smaller.
The power price in the model is higher than the one in the highlights. A kilowatt hour is the unit of electricity on a power bill. The highlights quote US$0.0315 a kilowatt hour. That is the charge for the energy alone. The financial model uses US$0.148, which includes paying the third party for the line [R2]. Both figures are in the same document. So moving the line out of the capital cost is not a saving. The project pays for it through the higher power price over the life of the mine.
The full build costs more than Stage 1. The US$4.25 billion is the cost of Stage 1 only. Stages 2 and 3 add US$3,441 million and US$3,473 million, for US$11,164 million in total. The study expects the later stages to be paid for partly from Stage 1's earnings.
The capital cost estimate is accurate to plus or minus 30 per cent, which is normal for a PFS. The study names 26 project risks and rates 16 of them high. It says the environmental and social impact assessment is expected to take up to six years. That assessment sets the timetable. It has to meet Newfoundland and Labrador's requirements. Canada's fast-track process covers only the federal part. It states that no offtake discussions have been concluded, which it puts down to the Development Agreement with Vale. An offtake agreement is a contract in which a customer commits to buy the product.
How the value moves with the price
Figure 5 uses the sensitivity table in the PFS. A 20 per cent fall in the benchmark iron ore price cuts the NPV from US$9.0 billion to US$4.8 billion, which is a fall of 46 per cent. The study does not publish what happens to the 15.2 per cent return in that case.

Iron Bear has said it will publish an updated PFS in the December quarter of 2026 with “materially improved financial outcomes and new operational scenarios” [R3]. The optimisation studies behind it are due in November.
7.00 — VALE LEAVES
The Vale agreement, the payments and the decision
The terms of the Development Agreement
The Development Agreement was signed in February 2025 [R5]. It had two phases. In Phase 1 Vale would pay US$18 million towards the PFS, drilling and environmental work, and earn nothing unless it went on. In Phase 2 a joint venture would form, Vale would take 30 per cent at once, and it would fund up to a further US$120 million for the BFS and the permitting. Its share would rise to 75 per cent when that money was spent, or earlier if Vale chose to take the project to a decision to mine.
The decision to build the mine would then have been Vale's. After that decision, Vale could buy the last 25 per cent at a fair market price, or arrange the build funding so that Iron Bear kept 25 per cent without dilution.
Vale's payments and decision
Vale paid the US$18 million in five instalments, the last on 21 August 2026. The PFS was published on 29 July. Iron Bear asked the ASX to halt trading in its shares on 11 September, ahead of an announcement. On 15 September it announced that Vale had completed Phase 1 and would not proceed to Phase 2 [R3]. The final notice arrived on 18 September [R4].
The board said “The Iron Bear Board believes that the decision by Vale to not proceed to Phase 2 is not related to the project itself but recent internal corporate developments at Vale beyond the control of Iron Bear”. The announcement does not quote a reason from Vale.
Paul Berend, the Managing Director, said in the same announcement “We are sad that this productive relationship with Vale is at an end. However, IBR's retention of 100% ownership unlocks exciting opportunities to secure future funding from industrial partners, institutional investors or off takers…”.
Iron Bear keeps 100 per cent of the project. Vale earned no interest. The company had A$15.3 million in cash on 11 September and said it had no need to raise capital in the near term [R3]. Iron Bear said the Phase 1 drilling can now be deferred by up to two years with no impact on project timelines [R3].
What the share price did
The shares closed at 6.7 cents the day before the PFS and at 4.5 cents on 10 September, the last trade before the halt. That is a fall of about a third while Vale was still a partner. On 15 September they closed at 2.4 cents, down 46.7 per cent in one session. The last price on 7 October 2026 was 2.3 cents [R11]. Figure 6 shows the price since January 2025.

Samso's chart piece of 28 September made the same observation. “Vale's departure is the second event on this chart, not the first. The price had already given back everything the study delivered before the market knew Vale was leaving” [R42].
8.00 — DOES IRON BEAR STILL NEED A PARTNER?
Samso's earlier view and Iron Bear's funding position now
What Samso said before
Samso's position was consistent from March 2025 to July 2026. The piece on the PFS, published on 31 July 2026, said “You need a big brother to come along this journey” [R38]. A piece on 1 July put it as “A quarter of a project Vale will build beats all of a project a junior could never build” [R39].
Parts of that coverage have been overtaken. The 1 July piece said Vale's funding “takes the biggest risk off the table”. An earlier piece in March 2025 said a company like Vale would not sign a binding agreement “only to walk away afterwards” [R43]. Vale completed the phase it had committed to and then declined the next one, which the agreement allowed it to do.
The Insight of 23 July 2026 said “the Vale agreement is staged rather than guaranteed”, and described Iron Bear as able to be “a company-maker and a value trap from the same spreadsheet, depending entirely on the funding path” [R40].
What the numbers say now
This part is Samso's reasoning from the published figures. It is not a statement by the company.
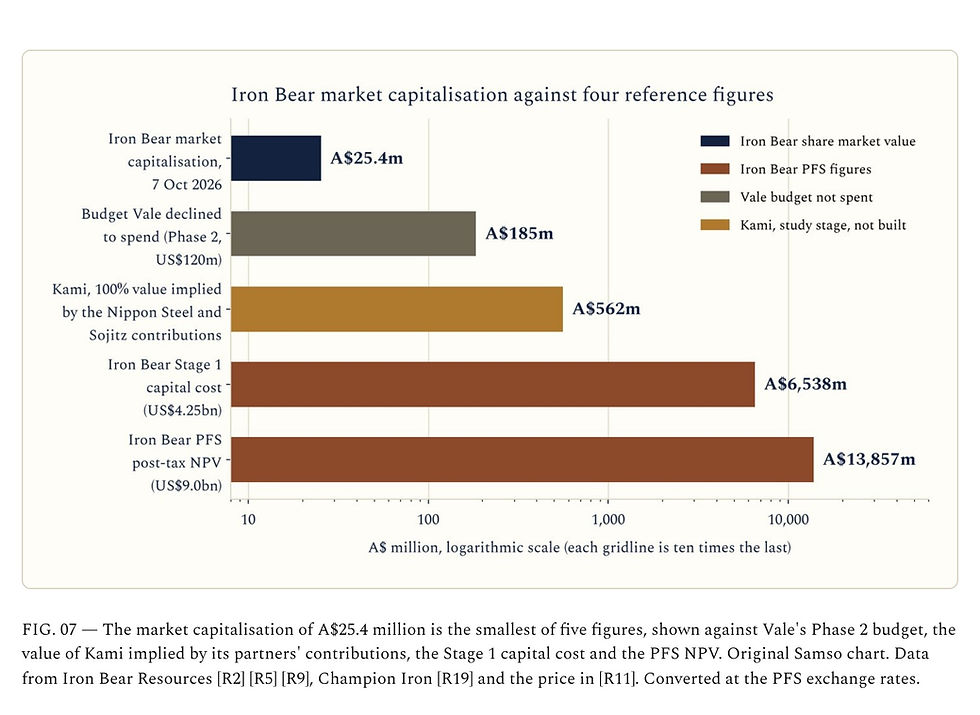
Vale's Phase 2 budget for the BFS and permitting was up to US$120 million. At the exchange rate the PFS uses, that is about A$185 million. Iron Bear has A$15.3 million. So the company holds about one-twelfth of the money that Vale had set aside for the next stage alone.
Stage 1 costs US$4.25 billion, or about A$6.5 billion. Iron Bear's market capitalisation is A$25.4 million. Market capitalisation is the share price multiplied by the number of shares. Stage 1 costs about 257 times that.
On those two figures the company cannot fund the next study from its cash, and cannot fund the mine. Iron Bear still needs outside funding.
What has changed since February 2025
Three things are different from February 2025, when the Vale agreement was signed.
The PFS exists and Iron Bear owns it. A new partner starts from a finished study and a declared reserve, both funded by Vale. The drilling planned for Phase 1 can be deferred and is still to be paid for.
No other party now holds a claim over the project. Under the old agreement 75 per cent was reserved for Vale, and Vale could match any offer a third party made for the rest. Other parties can now negotiate for any share.
The federal government has announced support for power and approvals in the region. The PFS assumed a third party would build a US$3.1 billion transmission line. In August 2026 the federal government committed C$10 billion of financing to hydro and transmission in the same region. Neither document says the Iron Bear line is part of that package.
A different kind of partner
Kami shows another structure. Champion kept 51 per cent. A steelmaker and a trading house took 49 per cent and are contributing cash for it. Vale is a miner that already sells DR pellets, so a new mine in Canada may have been one option among several for Vale.
Iron Bear said on 15 September that it intends to appoint a Tier 1 financial adviser to define a possible project financing package and to sign a cooperation agreement with an Indigenous group [R3]. Iron Bear's ASX announcements up to 8 October 2026 name no new partner. That is what we found, but we have not been able to verify whether anything has changed outside them.
SAMSO TAKE Iron Bear still needs a big brother. It no longer has to give one company three quarters of the project to get one. Could a steelmaker, a trading house or a government fund take a minority share and leave Iron Bear with more than the 25 per cent that the Vale agreement would have left it? |

9.00 — IRON BEAR'S MARKET CAPITALISATION
Iron Bear's market capitalisation against the tonnes, the PFS and Kami
Samso publishes no valuations and no price targets. What follows is arithmetic on published numbers, set out so that anyone can check it and disagree with it. Every figure for the project is for 100 per cent, which Iron Bear now owns.
The starting figures
Iron Bear had 1,106,253,248 shares on issue on 4 September 2026 [R9]. The last price on 7 October was 2.3 cents [R11]. Multiplying the two gives a market capitalisation of A$25.4 million. The company held A$15.3 million in cash on 11 September. Taking the cash away leaves about A$10 million as the price the market is putting on the project and everything else the company owns. The cash figure is four weeks old and is likely to be lower now.
The PFS uses an exchange rate of 65 US cents to the Australian dollar and 73 US cents to the Canadian dollar. Samso has used the same rates so the comparisons match the study.

Table 5 gives six comparisons. Figure 7 puts the market capitalisation beside four reference figures. Its Vale bar is the Phase 2 budget of A$185 million from section 8.00. The scale on that chart is logarithmic, which means each gridline is ten times the one before it. A normal scale would leave the first bar too small to see.
What the comparisons do and do not show
The Kami comparison is the strongest because two industrial companies made it with their money. They committed the equivalent of 87 Australian cents for each tonne of reserve at a PFS-stage project in the same district. The market is paying under one cent a tonne for Iron Bear's reserve.
Kami and Iron Bear differ in three ways. Kami is beside existing rail and power at Wabush, and Iron Bear is 250 kilometres further north. Kami has a 51 per cent owner that operates a mine next door and has cash flow. And only C$68.6 million of the C$245 million has been contributed. The rest depends on a study that is not finished.
The Vale and Kami sums are the same kind of money. Both were to be spent on the project, and neither was a payment to the owner. The US$138 million shows the terms on which a major took an option over 75 per cent in February 2025. The same major decided not to continue in September 2026.
The NPV comparison is the weakest. The NPV assumes the mine is funded, approved and built on the study's schedule. Iron Bear has none of the three. The gap between 0.18 per cent and 100 per cent reflects the chance the mine is never built, the new shares issued on the way, and whether the market accepts the study's prices and costs.
Is it the cheapest on the ASX?
On the potential in the ground against the price of the company, Samso thinks it may be. Against the tonnes in the ground, against its own study and against the Kami transaction, the market capitalisation is a small fraction of each figure.
Samso called the stock undervalued at A$50 million in April 2026 [R44] and at A$77 million on 31 July [R38]. In May it asked how many companies at this stage were valued at A$62 million [R45]. It is A$25.4 million now. A low price on these measures was no protection over those six months.
When the pellets would reach the market
The PFS gives two sets of dates. Its financial model assumes the mine is operating in 2035. Its power section targets 2031 to 2032 for the first stage. Both are quoted as published. Its allowance of four to six years to a decision to mine was written when Vale was the partner.
On the 2035 date the first DR pellets are made in about 2039, and the full 18.4 million tonnes a year is reached from about 2045. The BloombergNEF forecast in Table 1 has a shortfall of 15 million tonnes a year in 2030 and 133 million tonnes a year in 2040. Most of Iron Bear's pellets would arrive after the second date.
On that timetable the product would be sold from about 2039. The shares on issue between now and then are unknown. An option is a right to buy a new share at a set price. There are 370 million listed options that can be turned into shares at 3.2 cents until November 2028 [R9]. A BFS and permitting budget of up to twelve times the company's cash also has to be paid for by someone.
10.00 — THE CASE AGAINST
Green iron delays, the iron ore price, competing supply and Vale's decision
THE CASE AGAINST Green iron is running late. Thyssenkrupp paused its tender for hydrogen in March 2025 because the price was well above what it had assumed [R32]. Stegra, the Swedish green steel company, needed rescue financing of €1.4 billion in April 2026 and put its timetable under review [R31]. Each delay at a steel plant pushes back the date a DR pellet is needed. The iron ore price is the larger risk. The Simandou mine in Guinea shipped 5.7 million tonnes between January and 9 June 2026, against less than half a million tonnes in all of 2025 [R30]. S&P Global put the oversupply in the seaborne market at about 16 million tonnes. Figure 5 shows what a 20 per cent lower price does to the Iron Bear study. The tonnes likely to reach customers first are at ArcelorMittal and Champion. Both are converting mines that already run, on rail they already use. Figure 3 shows 17.5 million tonnes a year of DR-grade product from those two upgrades. On current timetables they reach customers ten years or more before Iron Bear's pellets. The outstanding risks are the environmental assessment, the ability to sell the product and the capital required to build the project [R2]. Vale funded the study and did not continue. Iron Bear's PFS describes Vale as the largest producer of DR pellets in the world [R2]. Vale paid US$18 million towards the PFS and then chose not to spend up to US$120 million more. The board believes the reason was internal to Vale. Iron Bear's announcement gives no reason from Vale. |
The defence of the project is in the same documents. The reserve is large and the concentrate meets the specification. A railway and a port exist, and the PFS includes upgrades to both. The federal government has committed financing for power in the region.
11.00 — SAMSO VIEW
What the IEEFA piece means for an Iron Bear shareholder
SAMSO TAKE The IEEFA piece is good news for the Labrador Trough and I think it is fair. Canada is backing the power and has a bill to shorten approvals. It has also listed high-purity iron ore as a critical mineral. Australia has not put iron ore on its critical minerals list. A government does not build the mine. Kami has partners and the two operators are upgrading their own mines. Iron Bear has the largest production plan of any project in the district and no partner. I said in July that Iron Bear needed a big brother. I still think so. I was wrong to treat Vale's cheque as the answer. It paid for a study and it bought Vale an option, and Vale did not take it up. Is this the cheapest mineral asset on the ASX? Put the potential value in the ground beside a market capitalisation of about A$25 million, and on those two things I think it is. This is not a valuation. It is a comment that the price of the company is very small for what it holds. The dates I am watching are the updated PFS in the December quarter, the Kami DFS, and whether Iron Bear is named in anything the Major Projects Office does. A new partner that leaves Iron Bear with more than 25 per cent would improve the picture. A capital raising at around two cents would weaken it. Will a partner arrive before the company needs more cash? Does a partner need to come for the company to make this work? Can the company actually do this on its own? I am a shareholder in Iron Bear Resources. Do your own research. |
THE VOCABULARY, IN PLAIN ENGLISH Blast furnace The traditional way to make iron. It burns coke made from coal and releases carbon dioxide. Direct reduction (DR) and DRI A process that removes oxygen from iron ore with gas, without melting it. The product is direct reduced iron. Electric arc furnace (EAF) A furnace that melts DRI or scrap steel with electricity. Green iron Direct reduced iron made using hydrogen and clean electricity. DR-grade Ore pure enough for direct reduction, at more than 66 per cent iron and ideally more than 67 per cent, with very little silica and alumina. Magnetite A magnetic iron mineral. It is low grade in the ground and can be upgraded to a very pure concentrate. Concentrate and pellets Concentrate is the iron-rich powder left after processing. Pellets are marble-sized balls made from it and baked hard. Fe The chemical symbol for iron. A grade of 62% Fe means 62 per cent of the weight is iron. Mt and Bt Million tonnes and billion tonnes. Mineral Resource and Ore Reserve A resource is what is estimated to be in the ground. A reserve is the part a study has shown can be mined at a profit. Indicated, Inferred and Probable Confidence levels. Inferred is the lowest for a resource and Indicated is the next. Probable is the lower of the two reserve levels. JORC The Australian code that sets how resources and reserves are reported. PEA, PFS, DFS and BFS The sequence of studies on a project, from the first rough estimate to the one a bank will lend against. NPV, IRR and discount rate NPV is a project's forecast cash, less its costs, counted in today's dollars. IRR is its yearly return. The discount rate is how much less a future dollar is counted for. Payback The time it takes a project to earn back what it cost to build. Offtake A contract in which a customer commits to buy a project's product. Market capitalisation The share price multiplied by the number of shares on issue. |
References and sources
Figures 1, 2 and 4 and Plate 1 are reproduced from Iron Bear Resources' ASX announcements, with the document and page given in each caption. Figures 3, 5, 6 and 7 are original Samso charts of published data. Figures marked S in Table 5 are Samso's own arithmetic. Each entry below opens with the marker used in the text.
[R1] Soroush Basirat, “Labrador Trough vs the Pilbara and South Australia: Who will win the green iron race?”, Institute for Energy Economics and Financial Analysis, 7 October 2026. ieefa.org
[R2] Iron Bear Resources, “Iron Bear Project PFS delivers outstanding results”, ASX announcement, 29 July 2026, 160 pages. PDF
[R3] Iron Bear Resources, “Completion of Phase 1 Development Agreement”, ASX announcement, 15 September 2026. PDF
[R4] Iron Bear Resources, “Receipt of final development agreement notice”, ASX announcement, 18 September 2026. PDF
[R5] Cyclone Metals, “Cyclone Metals and Vale execute Development Agreement”, ASX announcement, 17 February 2025. PDF
[R6] Iron Bear Resources, “Indicated Mineral Resource increased to 4.5BT @29% Fe”, ASX announcement, 12 May 2026. PDF
[R7] Cyclone Metals, “Iron Bear Project Scoping Study”, ASX announcement, 11 August 2025. PDF
[R8] Iron Bear Resources, “Canadian Government Initiatives Benefit Iron Bear Project”, ASX announcement, 24 September 2026. PDF
[R9] Iron Bear Resources, Annual Report to shareholders, 30 September 2026, pages 66 and 114. PDF
[R10] Iron Bear Resources, “Application for Project of National Significance”, ASX announcement, 3 June 2026. PDF
[R11] Iron Bear Resources share price and price history, from the market data feed used by the company's website, read 7 October 2026. A secondary source for the ASX price. ironbearresources.com
[R12] Prime Minister of Canada, “Prime Minister Carney announces the largest clean energy investment in North American history”, 17 August 2026. pm.gc.ca
[R13] Government of Canada, Major Projects Office, “Labrador Trough Clean Power, Critical Minerals and Infrastructure Corridor”, referred 17 August 2026. canada.ca
[R14] Government of Canada, “Government of Canada introduces legislation to transform how Canada builds”, 21 September 2026. canada.ca
[R15] Natural Resources Canada, “Government of Canada releases updated Critical Minerals List”, 10 June 2024. canada.ca
[R16] Labrador Iron Ore Royalty Corporation, results for 2025, 11 March 2026. labradorironore.com
[R17] Labrador Iron Ore Royalty Corporation, results for the second quarter of 2026, 5 August 2026. labradorironore.com
[R18] Champion Iron, results for the first quarter of its 2027 financial year, ASX announcement, 30 July 2026. PDF
[R19] Champion Iron, “Champion Iron forms a partnership for the Kami Project with Nippon Steel and Sojitz”, 29 September 2025. championiron.com
[R20] Champion Iron, third quarter results for its 2024 financial year, with the DRPF approval and the Kami project study, 30 January 2024. championiron.com
[R21] ArcelorMittal, “ArcelorMittal announces CAD$205 million decarbonisation investment in its flagship Canadian mining operations”, 3 November 2021. The 2025 production figure of 25.6 Mt is from ArcelorMittal's annual report on Form 20-F for 2025 (sec.gov). arcelormittal.com
[R22] The Logic, report on ArcelorMittal's Québec expansion and federal funding, 6 August 2026. A secondary source. thelogic.co
[R23] Scully Royalty Ltd, annual report on Form 20-F for 2024, which gives 3,060,800 tonnes shipped in 2024 as reported by the mine operator (sec.gov), and Tacora Resources company page. tacoraresources.com
[R24] Tata Steel Minerals Canada, operations page, undated, read October 2026. tatasteelcanada.com
[R25] Natural Resources Canada, “Iron ore facts”, updated 27 February 2026. canada.ca
[R26] Soroush Basirat, “Global high-grade iron ore market is set to grow”, IEEFA, 19 March 2026. ieefa.org
[R27] Chris Barrington, “The Iron Ore Challenge for Direct Reduction”, Direct From Midrex, June 2022. midrex.com
[R28] Midrex, “World DRI production reaches 151.0 Mt in 2025”, September 2026. midrex.com
[R29] MMi Daily Iron Ore Report, 8 September 2026, IOSI62 and IOSI65 indices. PDF
[R30] S&P Global Commodity Insights, report on Simandou exports, 17 June 2026. spglobal.com
[R31] ESG Today, report on the Stegra financing, April 2026. A secondary source. esgtoday.com
[R32] Eurometal, report on thyssenkrupp Steel pausing its green hydrogen tender, March 2025. A secondary source. eurometal.net
[R33] Red Paramount Iron, Lac Virot project summary and February 2025 PEA results. redparamount.ca
[R34] SteelOrbis, report on MetalQuest Mining starting DR pellet test work at Lac Otelnuk, September 2026. A secondary source. steelorbis.com
[R35] High Tide Resources, news release on the 2026 drilling at Labrador West, 30 September 2026. webdisclosure.com
[R36] Century Global Commodities, feasibility results for the Joyce Lake project, October 2022, and year-end filing, June 2026. miningstockeducation.com
[R37] Government of Canada, Major Projects Office, process infographic. PDF
[R38] Samso, “Iron Bear Resources (ASX:IBR) Maiden PFS: A 3.3 Billion Tonne Ore Reserve, a US$ 9 Billion NPV, and What It All Means”, 31 July 2026. samso.com.au
[R39] Samso, “Iron Bear Resources (ASX: IBR): Why Vale Is Funding Its Way to 75% of Iron Bear”, 1 July 2026. samso.com.au
[R40] Samso, “The Dilemma of Investing in the Iron Ore Story”, 23 July 2026. samso.com.au
[R41] Samso, “Direct Reduction (DR) Pellets and Green Steel – Who are the Industry Leaders?”, 22 April 2026. samso.com.au
[R42] Samso, “Iron Bear Resources (ASX: IBR) - What the Technical Traders See After the Vale Exit”, 28 September 2026. samso.com.au
[R43] Samso, “Cyclone Metals Limited (ASX: CLE)—Magnetite is the Age of Green Iron.”, 9 March 2025. samso.com.au
[R44] Samso, “Coffee with Samso – Iron Bear Resources Limited (ASX: IBR) – A Magnetite Story Positioned for Steel Decarbonisation”, 12 April 2026. samso.com.au
[R45] Samso, “Iron Bear Resources Limited (ASX: IBR) — Indicated Resource Doubles to 4.5 Billion Tonnes at 29.5% Fe and 20.6% Magnetic Fe at the Iron Bear Project”, 18 May 2026. samso.com.au
[R46] Champion Iron, “Champion Iron produces DR quality iron ore from its DRPF project and enters into commercial agreement”, 28 June 2026. championiron.com
Cover photo Iron Bear DR pellets after testing. Iron Bear Resources, “Iron Bear Project PFS delivers outstanding results”, ASX announcement, 29 July 2026, Figure 19, page 60.
 The Samso Way – Seek the ResearchHere at Samso, we pride ourselves on delivering content for investors that is independent and informed by over three decades of experience in the industry. Our content is well-researched and is only created if I see merit in discussing the company's story. Our mission is simple. Cut through the noise and spotlight what matters. Genuine stories, grounded insights, and real opportunity. Investors can explore our four core platforms:
There may be numerous paths to success in investing, but the common thread among successful individuals is that they remain committed to making informed decisions. Equip yourself with the right knowledge and tools, and you will be well on your way to achieving your financial goals. Most importantly, investors need to be absolutely diligent in understanding their own risk-reward tolerance and capabilities. Never bite off more than you can chew. As they say, Rome wasn't built in a day, and the Great Wall stood because it took centuries to complete. The Samso Philosophy: Stay curious. Stay sharp. And remember, digging deeper always uncovers the real value. In Life, there is no such thing as a Free Lunch. Never bite off more than you can chew is my parting comment. Happy Investing, and the only four-letter word you need to know is DYOR. To support our independent work, please head over to our Support Page and give us a helping hand in any of the ways listed. This is a new initiative for the Samso Platform, and it was always the concept of Samso when we started this journey in 2018. DisclaimerThis article is general information only. It is not financial product advice and it does not take into account any reader's objectives, financial situation or needs. It contains no price targets, no valuations and no recommendation to buy, hold or sell any security. The views expressed in this article, including the Samso Take, are Samso's own. We are entitled to hold them, and they are opinion. Readers should consider obtaining advice from a licensed financial adviser and should conduct their own research before making any investment decision. Samso and its associates may hold interests in companies mentioned. About SamsoSamso is a trusted platform that equips dedicated investors with up-to-date industry knowledge and insights from top CEOs and thought leaders. By staying informed on business advancements and market trends, investors can enhance their financial decisions through a combination of expert guidance and their own research. Coffee with Samso, Samso Insights, Samso News and Samso Research are four ways into the same work. Interviews, long-form research, short takes on announcements and company-specific studies. Every one of them is about how to think about investing rather than what to buy. Samso Insights | www.samso.com.au | An Investor Lens on ASX-Listed Companies Samso Insights are independent research commentary for general information only. Nothing in this article is financial product advice, and it does not take into account any reader's objectives, financial situation or needs. Figures are drawn from public sources believed reliable at the stated dates but are not guaranteed. Market-sensitive numbers change daily. Samso or associated parties may hold positions in, or have commercial arrangements with, companies mentioned. Seek professional advice before making investment decisions. © Samso 2026 · samso.com.au |

Comments