


ASX today, ASX 200 up 0.79%, tech shares gain 4.45%

Samso Market Update | Friday, 2 October 2026 | Market close 4:30pm AEST
The S&P/ASX 200 rose 67.7 points, or 0.79%, to 8,682.1 on the ASX today, Friday 2 October. Technology was the strongest sector, up 4.45%. The index fell 174.9 points on Thursday, so Friday's rise recovered about 39% of that fall (FIG. 01). The All Ordinaries, which covers the 500 largest listed companies, rose 60.3 points, or 0.69%, to 8,854.7. The Small Ordinaries, which covers companies ranked 101 to 300 by size, rose 17.7 points, or 0.53%, to 3,326.4.
ASX today: Key Highlights
The S&P/ASX 200 closed up 67.7 points, or 0.79%, at 8,682.1. ASX 200 futures had been up 45 points before the open. A futures contract is an agreement to buy or sell the index at a set date.
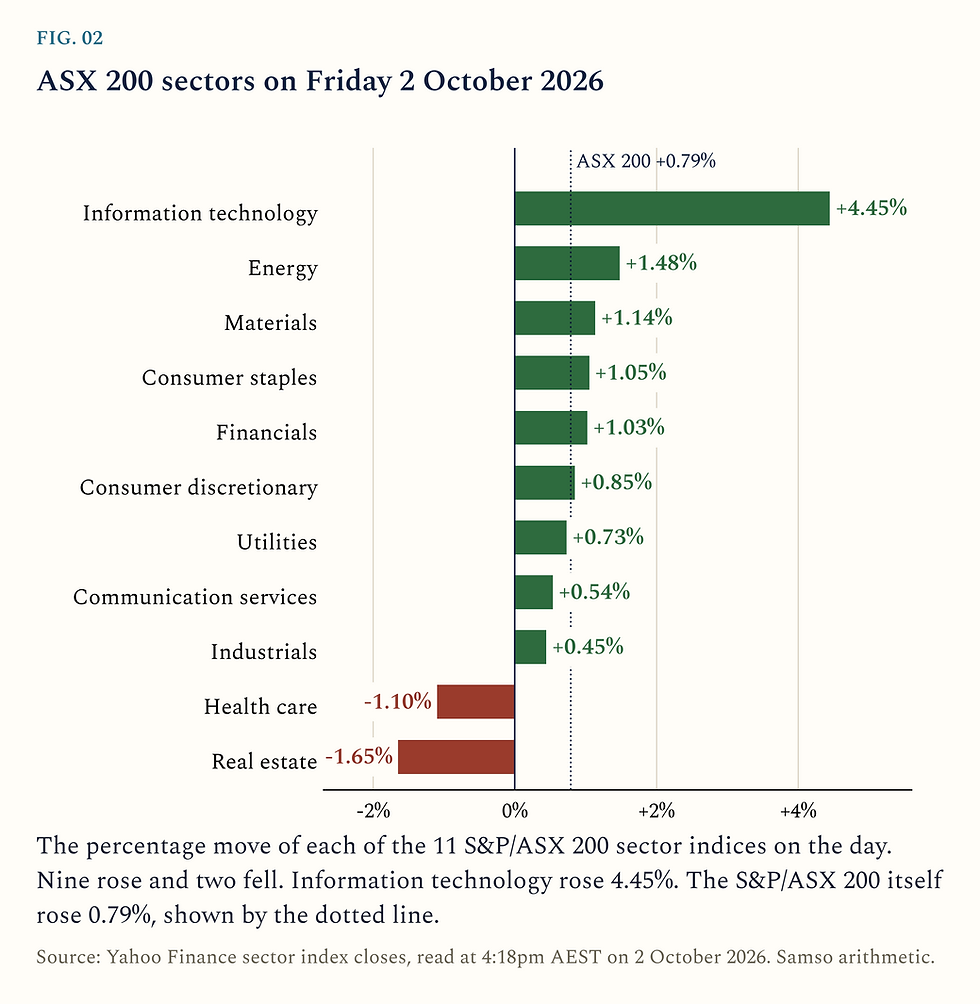
Nine of the 11 sectors rose. Information technology rose 4.45%. Real estate fell 1.65% and health care fell 1.10%.
Across 1,743 ASX-listed companies, 576 rose, 554 fell and 613 were unchanged.
Megaport (ASX: MP1) rose 10.3% to $22.34. Life360 (ASX: 360) rose 7.0% to $20.40. WiseTech Global (ASX: WTC) rose 6.7% to $33.43.
Mamba Exploration (ASX: M24) rose 57.8% to 7.1 cents on the day it released an investor presentation and notices of proposed share issues, which tell the market a company plans to issue new shares.
Iron ore fell 1.3% to US$91.10 a tonne, according to ABC News. Brent crude was about US$101.72 a barrel at 4:28pm AEST.

ASX 200 today, sectors and US bond yields
A Treasury is a US government bond. A bond's yield is the yearly return from buying it at today's price, and when yields rise, bond prices fall. ABC News reported that the local market was supported by Wall Street's recovery from early losses as US Treasury yields retreated from multi-decade highs. The US 10-year Treasury yield finished the US session at 5.24%, down from 5.29%, as set out in this morning's edition below.
The S&P/ASX 200 Information Technology index rose 4.45% to 1,742.7 (FIG. 02). Energy rose 1.48%, materials 1.14%, consumer staples 1.05% and financials 1.03%. Consumer discretionary rose 0.85%, utilities 0.73%, communication services 0.54% and industrials 0.45%. Real estate fell 1.65% and health care fell 1.10%. Index and sector figures are from Yahoo Finance at 4:18pm AEST.
No market-sensitive Australian economic data was scheduled for the session, and the ABC News live blog recorded no Reserve Bank of Australia announcement.
The ASX biggest movers follow in Samso's four size bands (TABLE 01). The bands are Samso's own and are set by market capitalisation, which is the value of all of a company's shares. The Small Caps band is separate from the Small Ordinaries index. Turnover is the dollar value of shares traded in the session.
Blue Chips (above A$1 billion)
The ASX top gainers in this band were technology companies. Elsight (ASX: ELS) rose 13.0% to $5.32 on turnover of about A$11.2 million. Megaport rose 10.3% to $22.34 on about A$51.4 million. Neither has made an ASX announcement since Thursday evening. On Tuesday Megaport released "Megaport Secures New AI Infrastructure Contracts".
Data#3 (ASX: DTL) rose 7.8% to $13.61. It released a first-half trading update at midday on Thursday, and ABC News reported that the company raised its profit forecast. Life360 rose 7.0% to $20.40 and WiseTech Global rose 6.7% to $33.43 on about A$56.1 million, the largest turnover among the band's top gainers. Life360 and WiseTech have made no ASX announcement since Thursday evening.
Among the ASX top losers in this band, EQ Resources (ASX: EQR) fell 10.1% to 40 cents on about A$22.3 million. Macmahon Holdings (ASX: MAH) fell 9.9% to $1.00. Neither has made an ASX announcement since Thursday evening. DPM Metals (ASX: DPM) fell 8.4% to $57.41 on the day it announced a decision of the Constitutional Court of Bosnia and Herzegovina. The release was lodged at 8:16am AEST, before the open. Benz Mining (ASX: BNZ) fell 8.4% to $4.70, with no ASX announcement since Thursday evening.
Mid Caps (A$500 million to A$1 billion)
Hansen Technologies (ASX: HSN) rose 9.6% to $3.42 on the day a substantial holder notice was lodged. A substantial holder is an investor with 5% or more of a company's shares. SHAPE Australia (ASX: SHA) rose 8.3% to $8.12 on about A$17.2 million, with no ASX announcement since Thursday evening. Artrya (ASX: AYA) rose 7.9% to $3.70 on the day it announced a commercial agreement with Huntsville Hospital Health System. Nuix (ASX: NXL) and Black Cat Syndicate (ASX: BC8) each rose 7.2%, to $1.93 and 74.5 cents. Nuix has made no ASX announcement since Thursday evening. Black Cat lodged a director's interest notice.
BMC Minerals (ASX: BMC) fell 3.8% to $2.75. Imricor Medical Systems (ASX: IMR) and PMET Resources (ASX: PMT) each fell 3.5%, to $1.505 and 41.5 cents. AIC Mines (ASX: A1M) fell 3.3% to 87 cents. BMC, Imricor and AIC have made no ASX announcement since Thursday evening. PMET lodged a routine statement of securities on issue.
ASX Small Caps (A$150 million to A$500 million)
Prospect Resources (ASX: PSC) rose 14.6% to 23.5 cents, with no ASX announcement since Thursday evening. On Thursday morning it reported copper drilling results from Nyungu Central. Amaero (ASX: 3DA) rose 9.4% to 17.5 cents. Praemium (ASX: PPS) rose 9.1% to 60 cents on the day it announced a change of chief executive. Tivan (ASX: TVN) rose 8.3% to 19.5 cents and Appen (ASX: APX) rose 7.3% to $1.25. Amaero, Tivan and Appen have made no ASX announcement since Thursday evening.
Vitrafy Life Sciences (ASX: VFY) fell 8.0% to $3.56 and Mayfield Group Holdings (ASX: MYG) fell 7.1% to $2.10, and neither has made an ASX announcement since Thursday evening. Cobre (ASX: CBE) fell 6.8% to 34.5 cents on the day it announced the completion of an A$90 million institutional capital raising. A capital raising is a sale of new shares for cash, and institutional means the buyers were professional investors such as funds. Healius (ASX: HLS) fell 6.0% to 39.5 cents, with no ASX announcement since Thursday evening.
Micro Caps (below A$150 million)
Mamba Exploration rose 57.8% to 7.1 cents on turnover of about A$2.25 million. Its market capitalisation was A$22 million at Thursday's close. Before the open it lodged an investor presentation and three notices of proposed share issues. Cannindah Resources (ASX: CAE) rose 17.4% to 2.7 cents and Nexsen (ASX: NXN) rose 13.0% to 13 cents, and neither has made an ASX announcement since Thursday evening.
Yandal Resources (ASX: YRL) fell 16.0% to 10.5 cents and EAU Lithium (ASX: EAU) fell 12.9% to 13.5 cents, and neither has made an ASX announcement since Thursday evening. Peregrine Gold (ASX: PGD) fell 9.1% to 15 cents on the day it announced a A$2.25 million capital raising to fund gold and iron exploration.
Shares priced below one cent are left out of this band. The smallest price change allowed, 0.1 of a cent, moves them by 10% or more.

Commodities and Currency
Futures prices are at about 4:28pm AEST, and each change is measured against the previous session's close (TABLE 02). The contract month is the month in which a futures contract falls due.

Samso Concluding Comments
Technology was the strongest of the 11 sectors, up 4.45%. ABC News linked the session to the easing in US Treasury yields overnight. Brent crude remained above US$100 a barrel. US jobs figures for September are due at 10:30pm AEST tonight, and Monday is the first ASX session after the release. Daylight saving starts in Sydney on Sunday, so from Monday the 4:00pm Sydney close is 1:00pm in Perth.
General information only. This is not financial advice.
The pre-market edition from earlier today follows below. The previous edition was ASX today, Thursday 1 October 2026.
Samso Market Update | Friday, 2 October 2026 | Pre-market 9:45am AEST
Futures point to a higher open on the ASX today, one day after the S&P/ASX 200 fell 1.99%. A futures contract is an agreement to buy or sell the index at a set date, and its overnight move is the usual guide to where shares open. ASX 200 futures were up 45 points, or 0.52%, at 8,678 at 8:36am AEST. The S&P/ASX 200 closed down 174.9 points at 8,614.4 on Thursday. The All Ordinaries, which covers the 500 largest listed companies, fell 1.95% to 8,794.4. The Small Ordinaries, which covers companies ranked 101 to 300 by size, fell 1.78% to 3,308.7. The Australian dollar was at approximately 69.3 US cents at 8:45am AEST.
ASX today: Key Highlights
ASX 200 futures were up 45 points, or 0.52%, at 8:36am AEST, after Thursday's 1.99% fall to 8,614.4.
The yield on the US 10-year Treasury, a US government bond, eased to 5.24% from 5.29%. During the session it touched its highest level since 2002.
Wall Street closed slightly higher (FIG. 01). The S&P 500 rose 0.19% and the Dow Jones and Nasdaq each rose 0.04%.
Japan's Nikkei 225 rose 3.3% on Thursday. London's FTSE 100 fell 1.68%.
Brent crude for December delivery rose approximately 4.5% to approximately US$102.50 a barrel.
US jobs figures are due at 10:30pm AEST tonight, after the local market has closed.

Wall Street overnight
The Dow Jones Industrial Average rose 20.51 points, or 0.04%, to 50,926.56. The S&P 500 rose 14.91 points, or 0.19%, to 7,666.45, which Market Index reported as the end of a three-session run of falls. The Nasdaq Composite rose 10.53 points, or 0.04%, to 26,871.60. The Russell 2000, an index of smaller US companies, rose 0.35% to 2,806.63.
The US 10-year Treasury yield finished at 5.237%, down approximately 6 basis points from 5.293% (FIG. 02). A basis point is one hundredth of a percentage point. A bond's yield is the yearly return from buying it at today's price, and when yields rise, bond prices fall. TheStreet reported the yield reached approximately 5.33% earlier in the session, its highest level since April 2002. Market Index reported that the main US indices recovered early losses once yields eased.

Two US data releases came out during the session. The ISM manufacturing index, a monthly survey of factory activity, was 54.5 against a forecast of 55.0. Its prices paid measure rose to 77.9 against a forecast of 73.0, according to Market Index. Initial jobless claims were 197,000.
Japan
The Nikkei 225 closed at 68,956.72 on Thursday, up 2,203 points, or 3.3%. News On Japan attributed the rise to buying in semiconductor and artificial intelligence shares following the earnings outlook from US chipmaker Micron Technology. The same report said the Tankan, the Bank of Japan's quarterly survey of business confidence, was at its strongest level in eight years. The US dollar bought approximately 158.06 yen at 8:46am AEST, against 157.56 in the previous session.
London and Europe
The FTSE 100 closed down 177.73 points, or 1.68%, at 10,428.27. Germany's DAX fell 1.03% to 24,939.35. France's CAC 40 fell 1.62% to 7,835.31.
Currencies
The Australian dollar was at approximately 69.3 US cents at 8:45am AEST. It was 69.46 US cents in the previous session and 70.16 US cents three sessions ago. The US dollar index, which measures the US dollar against six major currencies, rose 0.58% to 102.04. Market Index reported this as its fourth daily gain in a row. The US dollar bought approximately 158.06 yen.
Commodities
Prices are futures prices at approximately 8:37am AEST (TABLE 01). The contract month is the month in which a futures contract falls due.

Market Index reported that Brent moved above US$102 a barrel (FIG. 03) following comments by US President Donald Trump on potential strikes on Iran. TheStreet reported that Chinese refiners had suspended fuel exports.

Samso Insight: where the gold price settles before its next move
Today's diary
11:30am AEST. The Australian Bureau of Statistics releases Deaths, Australia for 2025. No market-sensitive Australian data is scheduled.
7:00pm AEST. Eurozone preliminary inflation for September.
10:30pm AEST. US non-farm payrolls and the unemployment rate for September.
Daylight saving starts in Sydney on Sunday. From Monday the ASX opens at 10:00am AEDT, which is 7:00am in Perth.
Samso Concluding Comments
ABC News attributed Thursday's fall on the ASX to higher oil prices pushing bond yields up around the world. In the US session that followed, the 10-year yield touched its highest level since April 2002, then eased to 5.24%. ASX 200 futures rose 45 points, approximately a quarter of Thursday's 174.9-point fall. December Brent rose approximately 4.5%. The US jobs figures are due at 10:30pm AEST, after the ASX has closed. Monday is the first ASX session after the release.
General information only. This is not financial advice.
Previous edition: ASX today, Thursday 1 October 2026

Comments